Pricing on request | Late 2029
Uribe Schwarzkopf | Miami
WOMA
A new development by Uribe Schwarzkopf in Wynwood (Wynwood Norte), Miami, Miami-Dade County. Residences, pricing, the deposit schedule and what the developer is offering right now, with me on your side from the first visit to the sales gallery.
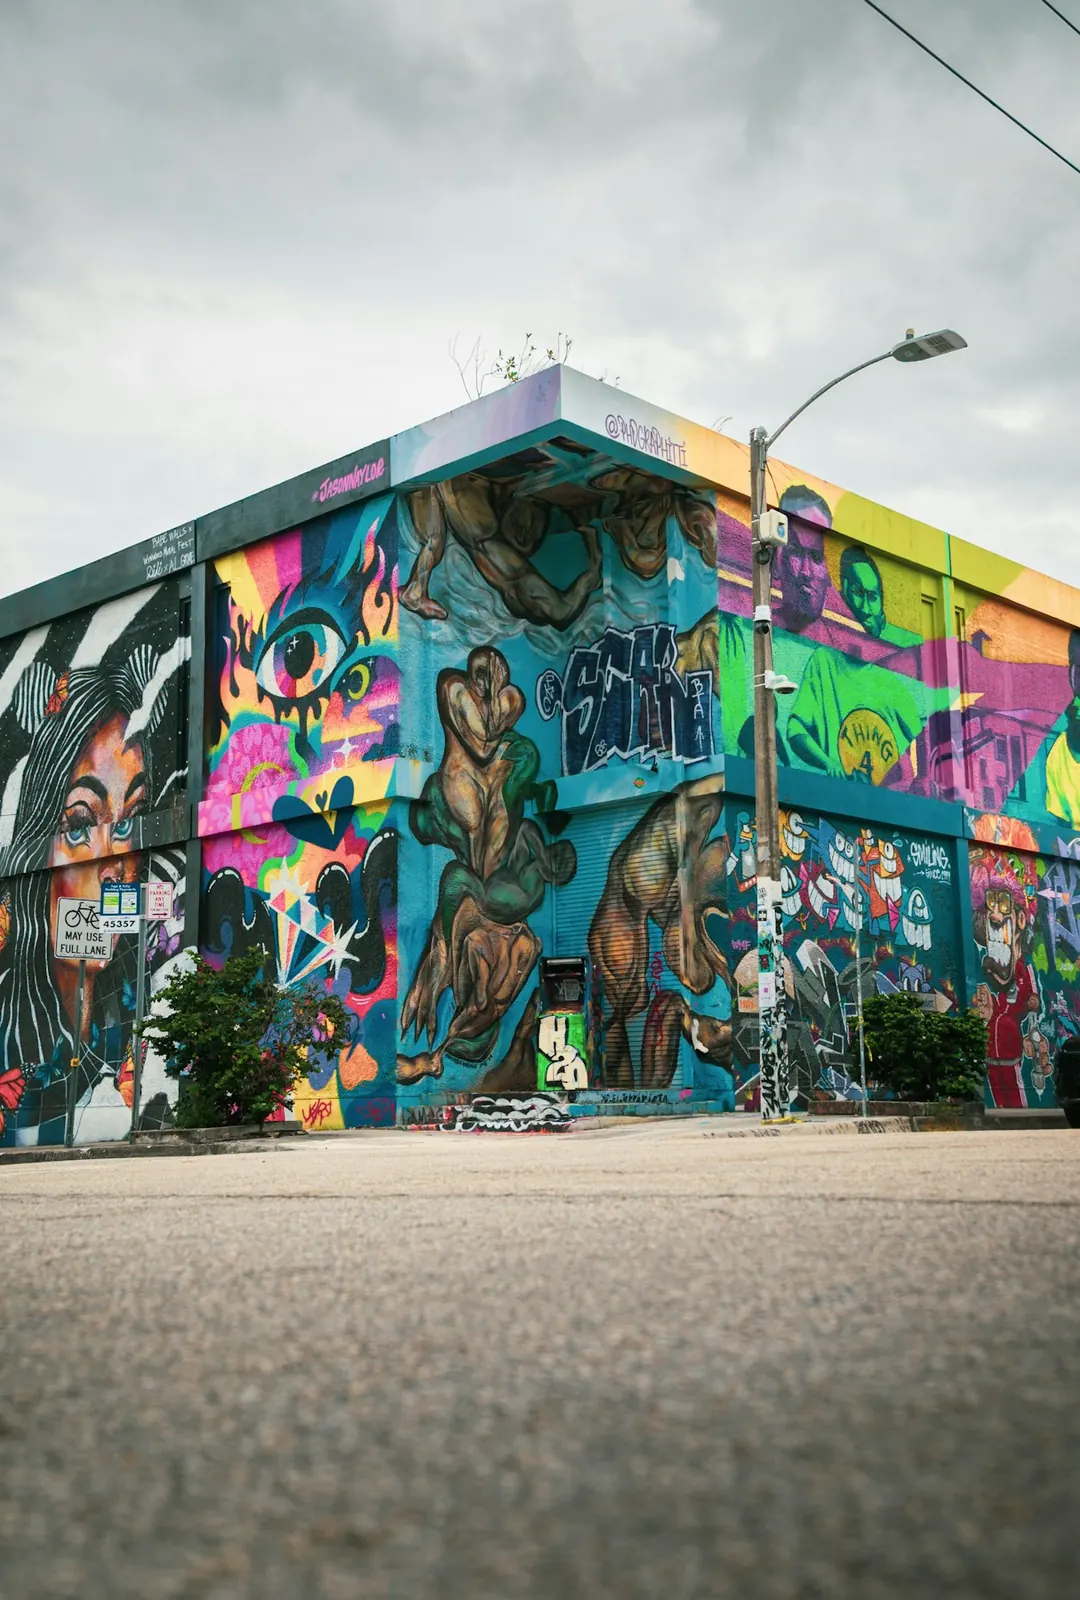
Envision your life at WOMA
Six stories in Wynwood Norte mixing 163 residences with shops and offices
In Wynwood Norte, WOMA is a six-story mixed-use building from Uribe Schwarzkopf, the developer's first project in the United States. You would choose from 163 residences, including four duplex ateliers, and the building also holds 13 retail spaces and 16 offices, so your address shares its walls with shops and workplaces. Sales have launched, groundbreaking is planned for 2027, and delivery is targeted for late 2029. If the duplex ateliers interest you, ask me, and I will walk you through those four first, since there are so few of them. Ask me for the floor plans, the amenity program and the current schedule.
01 The building
About WOMA
01
The area
WOMA is in Wynwood (Wynwood Norte), Miami, in Miami-Dade County. Wynwood, Midtown and the Design District sit north of downtown Miami between I-95 and Biscayne Boulevard, from about NE 20th Street to NE 43rd Street, with the Upper East Side running north along the bay to the Miami Shores line and the Julia Tuttle Causeway leading across to Miami Beach.
02
The location
It sits in Wynwood (Wynwood Norte). The developer shares the sales gallery address by appointment, and I'll set up the visit.
03
The residences
Uribe Schwarzkopf is building new development residences in a 6-story building with 163 residences, pricing on request. Late 2029.
04
The details
Six-story mixed-use building with 163 residences, including four duplex ateliers. 13 retail spaces and 16 offices. Developer's first US project. Sales launched. Groundbreaking planned for 2027.
02 The incentives
What Uribe Schwarzkopf is offering
Uribe Schwarzkopf isn't publishing a specific offer for WOMA right now. Builders and developers often have room that never makes the website, and I ask for it.
Offers as shown on the developer's website on October 26, 2026. Offers change often, may require the preferred lender, and have conditions set by the developer. I confirm what applies before you sign anything.
03 The residences
Residences and pricing
Floor plans, the current price list and the deposit schedule are on request. Ask and I will send them along with what Uribe Schwarzkopf is offering this month.
Starting prices are the developer's published pricing before floor and view premiums, and the developer may change prices and release new lines at any time. Source: public listings and reporting, checked October 26, 2026. Confirm current figures before you visit.
04 The payment
What's a comfortable monthly payment for you?
Start with the payment that feels right, or with a home price, and see the whole picture: principal and interest, property taxes, insurance, mortgage insurance and HOA dues. Then see how a builder's rate buydown changes the first years.
Rate starts at the Freddie Mac weekly average for a 30-year fixed loan, 7.32% (15-year: 6.68%), as of October 22, 2026. It's a reference point, not a quote. Change it to anything you like.
Taxes, insurance and HOA
Starting values: a property tax of 1.7% of the price, a planning figure from Miami-Dade's 2025 total millage of about 15.5 to 22.4 mills after the homestead exemption; Homestead and Florida City run near 21 (Miami-Dade Property Appraiser, tax year 2025). Home insurance of $4,200 a year, near Citizens' 2026 approved Miami-Dade average for a homeowners policy ($4,116) and adjusted for new construction built to the High-Velocity Hurricane Zone code. HOA and CDD of $250 a month, near the middle of published Miami-Dade new-community fees. Private mortgage insurance usually runs $30 to $70 a month per $100,000 borrowed (Freddie Mac), so 0.60% sits in the middle. FHA uses 0.55% a year plus a 1.75% upfront premium (HUD). Flood insurance is extra where a lender requires it.
Homes up to about
$0
How a builder buydown works
Lower payments in the first years
With a temporary buydown, the builder pays money up front so your rate starts lower and steps up to the full rate. A 2-1 buydown starts two points lower in year one and one point lower in year two. A 1-0 buydown is one point lower for the first year. Here's what it does on the loan above.
| Year | Rate | Principal and interest |
|---|
For illustration only. These are estimates from the numbers you enter, not a loan estimate, a quote, an advertisement of credit terms or an offer to lend. Your rate, APR and payment depend on your credit, loan program, down payment, lender fees and the property, and taxes, insurance, flood coverage, HOA dues and CDD assessments vary by home, building and county. The Wulf Collaboration and Compass are not lenders. Talk with a licensed lender before you decide.
Before you visit a model or a sales gallery
The builder's team works for the builder
The sales team in the model home or the sales gallery is great at what they do, and their job is to sell the builder's homes or the developer's residences. Having your own agent costs you nothing extra in most cases, and it puts someone on your side for the decisions that matter most.
Most builders and developers need your agent with you, or registered, at your first visit. If you walk in on your own first, it can be hard to bring an agent in later. A quick text to 954-495-0767 before you go is all it takes.
Register you at the first visit
I set up the appointment, come with you, and make sure you're on record as my client.
Compare communities, homesites and floors
Lake and preserve premiums, which way the home or residence faces, what's planned next door, HOA and CDD fees and what they cover.
Work the builder's offer
Closing cost help, design credits, rate buydowns and deposit terms. I know what each builder and developer is offering this month and what's worth asking for.
Review the purchase agreement
Builder and developer contracts are written by the seller. We go through deposits and escrow, timelines, the 15-day review on a new condominium, and what happens if dates move.
Inspect during construction
An independent inspector before drywall and again before closing, so problems get fixed while they're easy to fix.
Walk the punch list with you
The final walkthrough, then the warranty list before your first year is up.
WOMA
See it in person with me
I'll set up a visit to WOMA, send you current pricing and what Uribe Schwarzkopf is offering, and make sure you're registered as my client from the first step.
Got it
I'll be in touch shortly with your hand-picked list.
One tip while you wait: if you visit a model home or a sales gallery before we talk, send me a quick text at 954-495-0767 first, so I'm registered with you.

Representative photo
Model home and sales gallery visits
See it in person, with me
Pick a community or a tower and a day. I'll set up the visit, meet you there and make sure you're registered as my client from the first step through the door.